Smart Retirement Planning in 2026: Increasing Your 401(k) Contributions by 2% for Greater Security
Are you looking ahead to 2026 with an eye towards a more secure and comfortable retirement? If so, you’re on the right track. Proactive planning is the cornerstone of financial well-being in your golden years. One of the most impactful, yet surprisingly simple, strategies you can adopt is to significantly boost your 401k contribution increase. Specifically, aiming to increase your 401(k) contributions by just 2% can create a ripple effect that profoundly enhances your long-term financial security. This isn’t just about saving more; it’s about leveraging the power of compound interest, tax advantages, and consistent effort to build a robust retirement nest egg. Let’s delve into why a small adjustment in your 401(k) contributions can make such a monumental difference and how you can seamlessly integrate this change into your financial plan for 2026.
Anúncios
The concept of a 401k contribution increase might seem daunting, especially if you feel like your budget is already stretched thin. However, a mere 2% adjustment is often less noticeable in your day-to-day finances than you might imagine, yet its impact over decades can be truly transformative. We’ll explore the mechanics behind this strategy, from understanding the power of compounding to navigating employer matching programs and optimizing your tax situation. By the end of this comprehensive guide, you’ll have a clear roadmap to implement this vital step towards a more prosperous retirement.
The Compounding Power of a 2% 401k Contribution Increase
The magic of retirement savings lies in compound interest. Often referred to as the eighth wonder of the world, compound interest allows your money to grow exponentially as your earnings generate their own earnings. When you make a 401k contribution increase, even a small one like 2%, you’re not just adding to your principal; you’re increasing the base upon which future returns are calculated. This seemingly minor bump in contributions, sustained over many years, can lead to a surprisingly significant increase in your total retirement savings.
Anúncios
Let’s consider a hypothetical scenario. Imagine you earn $70,000 annually and currently contribute 8% of your salary to your 401(k). This amounts to $5,600 per year. If you decide to implement a 401k contribution increase by adding just 2%, bringing your total contribution to 10%, you’d be contributing an extra $1,400 per year ($7,000 total). While $1,400 might not seem like a game-changer on its own, when invested over 20, 30, or even 40 years with an average annual return of 7%, that additional $1,400 per year can grow into hundreds of thousands of dollars. The earlier you start, the more time compound interest has to work its magic, turning modest, consistent increases into substantial wealth.
Think of it this way: the initial 2% increase in your 401k contribution increase becomes a larger and larger percentage of your total growth over time. The money you contribute today has the longest runway for growth. Delaying this small increase means losing out on years of potential compounding. This is why 2026 is the perfect time to commit to this strategic adjustment – it gives your money more time to work for you.
Understanding Your 401(k) and Employer Match
Before making any adjustments, it’s crucial to have a clear understanding of your current 401(k) plan. Many employers offer a matching contribution, which is essentially free money for your retirement. For instance, an employer might match 50 cents on the dollar for the first 6% of your salary contributed. If you’re not contributing at least enough to get the full employer match, you are leaving money on the table. This is the absolute first step before considering any additional 401k contribution increase.
Once you’ve maximized your employer match, then a 2% 401k contribution increase becomes even more powerful. It’s additional savings on top of the ‘free money’ from your employer. This strategy ensures you’re not only taking full advantage of your benefits but also proactively building your personal retirement fund. Review your plan documents or speak with your HR department to understand your specific employer match policy and ensure you’re maximizing it.
It’s also important to understand the investment options within your 401(k). While increasing your contributions is vital, ensuring your money is invested appropriately for your risk tolerance and time horizon is equally important. Most 401(k) plans offer a range of funds, from target-date funds (which automatically adjust their asset allocation as you get closer to retirement) to various stock and bond funds. A well-diversified portfolio, even with a small 401k contribution increase, will yield better results than a poorly allocated one.
Practical Steps to Implement Your 2% 401k Contribution Increase in 2026
Implementing a 2% 401k contribution increase is often simpler than people realize. Most employers provide an online portal or a dedicated HR representative where you can adjust your contribution percentage. Here’s a step-by-step guide:
- Locate Your 401(k) Account Information: Access your company’s HR portal or your 401(k) provider’s website. You’ll typically find sections for ‘Retirement Savings,’ ‘Benefits,’ or ‘Payroll Deductions.’
- Identify Your Current Contribution Rate: Note down your current percentage contribution.
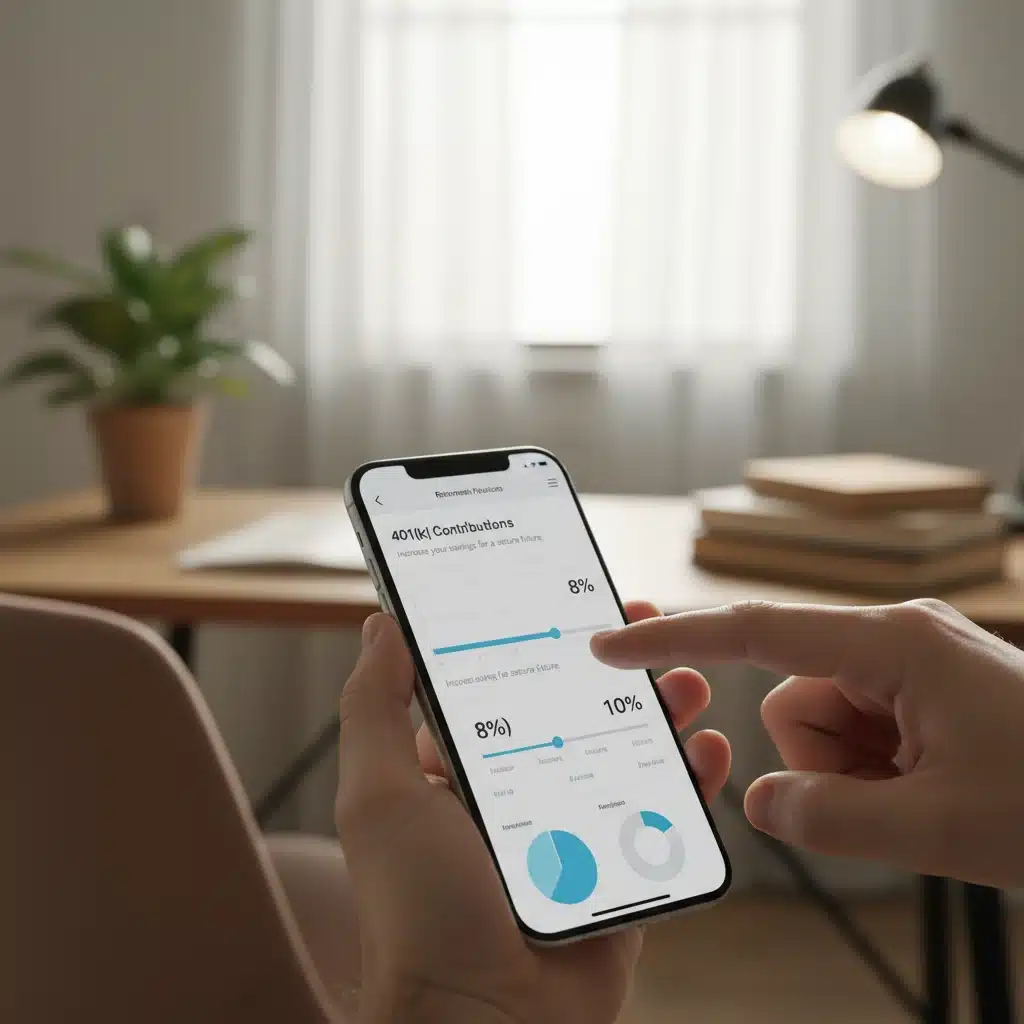
- Calculate Your New Contribution Rate: Add 2% to your current rate. For example, if you’re contributing 8%, your new target will be 10%.
- Adjust Your Contribution: Find the option to change your contribution percentage and update it to your new target. Most systems allow you to do this electronically.
- Confirm and Save: Double-check that the new percentage is correctly entered and save your changes. You might receive an email confirmation of the update.
- Review Your Paycheck: After your next pay cycle, review your pay stub to ensure the new deduction amount is reflected accurately.
Consider timing this 401k contribution increase with a salary raise or bonus. This strategy, known as ‘paying yourself first,’ makes the increase almost imperceptible to your take-home pay. If you automatically increase your contributions when your income rises, you won’t miss the money because you never got used to having it in your checking account. This psychological trick can make sticking to your new savings goal much easier.
The Impact on Your Take-Home Pay and Budget
One of the primary concerns when considering a 401k contribution increase is how it will affect your immediate finances. Let’s demystify this. For someone earning $70,000 annually, a 2% increase in contributions translates to an additional $1,400 per year. Divided by 26 bi-weekly paychecks, this is approximately $53.85 per paycheck. For many, finding an extra $50-60 per paycheck might require a small adjustment, but it’s often achievable by cutting back on non-essential expenses like a few fewer takeout meals, subscriptions you don’t use, or daily coffee runs.
Moreover, 401(k) contributions are typically pre-tax, meaning your taxable income is reduced by the amount you contribute. This reduces your overall tax liability, slightly offsetting the impact on your take-home pay. So, while your gross pay deduction increases, the net impact on your paycheck is slightly less than the full 2% increase due to tax savings. This tax efficiency makes a 401k contribution increase even more appealing.
To help visualize this, consider using an online retirement calculator. Many financial institutions offer tools that can show you the projected growth of your 401(k) with different contribution rates. Seeing the potential future value of your increased contributions can be a powerful motivator and help you adjust your budget accordingly. Remember, this isn’t about deprivation; it’s about prioritization and making smart choices that benefit your future self.
Long-Term Benefits Beyond Just More Money
While the most obvious benefit of a 401k contribution increase is a larger retirement nest egg, there are several other long-term advantages:
- Enhanced Financial Confidence: Knowing you’re actively working towards a secure retirement can significantly reduce financial stress and boost your overall sense of well-being.
- Greater Flexibility in Retirement: A larger savings balance provides more options. You might be able to retire earlier, maintain a higher standard of living, or have the flexibility to pursue hobbies and travel without financial constraints.
- Protection Against Inflation: Retirement savings that grow over time help combat the eroding effects of inflation. Your future purchasing power will be better preserved with more substantial savings.
- Potential for Catch-Up Contributions: Once you reach age 50, the IRS allows for additional ‘catch-up’ contributions to your 401(k). By already having a strong savings habit with your 401k contribution increase, you’ll be better positioned to take advantage of these higher limits as you approach retirement.
- Legacy Planning: For some, a robust retirement fund can also play a role in legacy planning, allowing you to leave a financial gift for loved ones or charitable causes.
These benefits extend far beyond simple monetary gain, contributing to a more fulfilling and worry-free retirement experience. The peace of mind that comes with knowing you’ve taken concrete steps to secure your future is invaluable.
Addressing Common Obstacles and Staying Consistent
Even with the best intentions, maintaining a consistent 401k contribution increase can face obstacles. Life happens: unexpected expenses, economic downturns, or changes in employment. Here’s how to navigate these challenges:
- Automate Everything: The best way to stay consistent is to automate your contributions. Once you set your 2% 401k contribution increase, it will automatically be deducted from each paycheck, removing the temptation to spend that money elsewhere.
- Revisit Annually: Make it a habit to review your retirement savings plan annually, perhaps at the beginning of each year or during open enrollment season. This allows you to assess if further increases are possible, especially after raises or bonuses.
- Build an Emergency Fund: A robust emergency fund (typically 3-6 months of living expenses) is crucial. It acts as a buffer against unexpected costs, preventing you from needing to tap into your 401(k) or reduce contributions during a crisis.
- Educate Yourself: The more you understand about investing, compound interest, and retirement planning, the more motivated you’ll be to stick to your goals. Read articles, listen to podcasts, or consult with a financial advisor.
- Stay Focused on Your Goals: Keep your retirement vision clear. Whether it’s traveling the world, spending more time with family, or pursuing a passion project, having a strong ‘why’ will help you stay disciplined with your 401k contribution increase.
It’s okay if you occasionally need to pause or slightly reduce your contributions due to unforeseen circumstances. The key is to get back on track as soon as possible. Consistency over the long term is far more important than perfection in the short term. The goal is to make the 2% 401k contribution increase a sustainable habit.
Comparing 401(k) with Other Retirement Vehicles
While focusing on your 401k contribution increase is excellent, it’s also worth understanding how it fits into your broader retirement strategy. Other popular retirement vehicles include:
- IRAs (Individual Retirement Arrangements): Both Traditional and Roth IRAs offer different tax advantages. Traditional IRA contributions are often tax-deductible, and earnings grow tax-deferred. Roth IRA contributions are made with after-tax money, but qualified withdrawals in retirement are tax-free. They also have lower contribution limits than 401(k)s.
- HSAs (Health Savings Accounts): If you have a high-deductible health plan, an HSA can be a triple-tax-advantaged savings vehicle. Contributions are tax-deductible, earnings grow tax-free, and withdrawals for qualified medical expenses are tax-free. Many people use HSAs as a supplemental retirement account, especially for healthcare costs in retirement.
- Brokerage Accounts: For those who have maxed out their tax-advantaged accounts, a taxable brokerage account can be a good option for additional savings. While not offering the same tax benefits, they provide flexibility and no contribution limits.
For most people, maximizing employer match in a 401(k) and then contributing to an IRA (often a Roth IRA if eligible) is a common strategy. After that, further increasing your 401k contribution increase or utilizing an HSA or taxable brokerage account makes sense. The optimal strategy depends on your income, age, financial goals, and access to different plans.
Forecasting Your Retirement with an Enhanced 401(k)
One of the most motivating aspects of a 401k contribution increase is seeing the projected impact on your future. While exact figures are impossible to predict, financial models can provide valuable insights. Let’s revisit our earlier example:
- Current Scenario (8% contribution): An individual earning $70,000, contributing 8% ($5,600/year) for 30 years with a 7% annual return, might accumulate approximately $566,000.
- Increased Scenario (10% contribution): The same individual, with a 2% 401k contribution increase to 10% ($7,000/year) for 30 years with a 7% annual return, could accumulate around $708,000.
This is a difference of over $140,000, all from a seemingly small 2% adjustment! These figures are illustrative and don’t account for employer matching, salary increases, or inflation, which would likely make the difference even more significant. The key takeaway is the substantial impact of consistent, slightly higher contributions over time.
To get a personalized forecast, utilize the retirement planning tools available through your 401(k) provider or reputable financial websites. Input your specific details, including your current balance, current contribution rate, proposed 401k contribution increase, and desired retirement age. These tools can help you visualize your progress and adjust your strategy as needed to meet your retirement income goals.
Conclusion: Secure Your Future with a Smart 2% Increase
As you plan for 2026 and beyond, remember that small, consistent actions can lead to extraordinary long-term results. Implementing a 2% 401k contribution increase is one of the most effective and accessible strategies to significantly enhance your retirement security. It leverages the power of compound interest, maximizes tax advantages, and builds a stronger foundation for your future.
Don’t underestimate the power of this seemingly minor adjustment. Take the time to review your current 401(k) contributions, understand your employer match, and make the simple change to boost your savings. Your future self will undoubtedly thank you for the foresight and discipline you apply today. Start 2026 with a renewed commitment to your financial well-being, and watch your retirement dreams become a more tangible reality.
By focusing on a consistent 401k contribution increase, you’re not just saving money; you’re investing in your peace of mind, your freedom, and your ability to live the retirement you’ve always envisioned.


