Understanding Your Rights: The 90-Day Window for Challenging Credit Report Errors in 2026
In the intricate world of personal finance, your credit report stands as a crucial document, a detailed chronicle of your borrowing and repayment history. It dictates everything from your ability to secure a loan for a new home or car to the interest rates you’ll pay on credit cards. Given its profound impact, the accuracy of your credit report is paramount. Unfortunately, errors are not uncommon, and they can have significant, detrimental effects on your financial well-being. This is where the concept of the 90-day credit challenge comes into play, a critical period that consumers must understand to protect their financial health, especially as we look towards 2026.
Anúncios
The landscape of credit reporting is constantly evolving, with new regulations and technological advancements shaping how information is collected, processed, and disputed. While the fundamental rights granted by acts like the Fair Credit Reporting Act (FCRA) remain steadfast, the practical application and consumer awareness of these rights are more important than ever. This comprehensive guide will delve into the specifics of the 90-day credit challenge, explaining why this timeframe is so vital, how to navigate the dispute process effectively, and what you need to know to empower yourself against credit report inaccuracies in 2026.
The Significance of Your Credit Report in 2026
Before we dive into the mechanics of the 90-day credit challenge, let’s briefly reiterate why your credit report is so important. In 2026, as digital transactions and automated lending continue to expand, your credit report serves as an even more immediate gatekeeper to financial opportunities. Lenders, landlords, insurers, and even some employers use credit reports to assess your reliability and financial responsibility. A single error, whether it’s an incorrect late payment, a fraudulent account, or a misreported balance, can drag down your credit score, leading to higher interest rates, denied applications, and increased financial stress.
Anúncios
Moreover, identity theft remains a persistent threat. Unscrupulous individuals can open accounts in your name, leaving you with a trail of debt and negative entries on your credit report. Early detection and prompt action, often within that crucial 90-day credit challenge window, are your best defenses against such financial attacks. Understanding how to monitor your credit and react swiftly to discrepancies is a fundamental skill for modern financial literacy.
What is the 90-Day Credit Challenge?
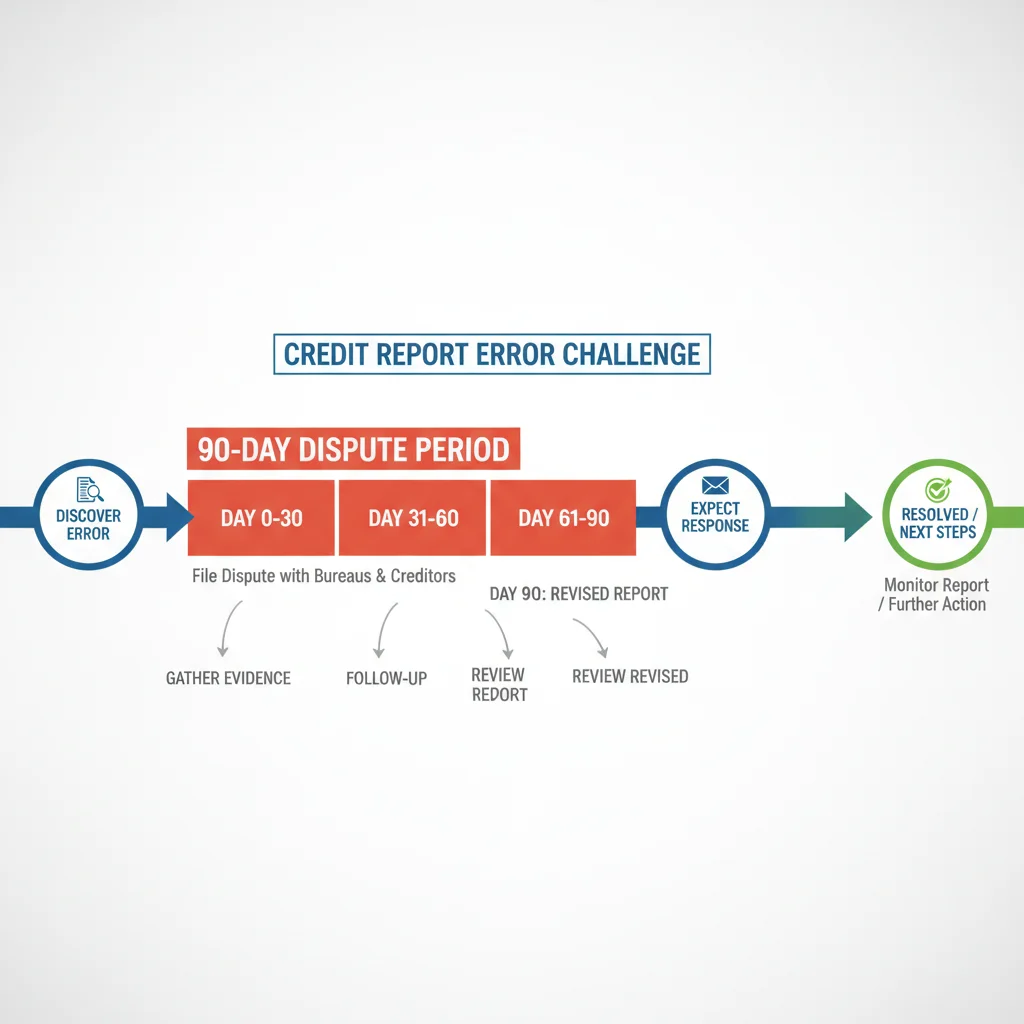
The phrase "90-day credit challenge" isn’t a strict legal deadline imposed by a single statute, but rather a widely recognized best practice and an aggregation of various timelines and recommendations that underscore the importance of prompt action when disputing credit report errors. While the FCRA mandates that credit bureaus investigate disputes within 30 days (and sometimes up to 45 days under certain circumstances), the 90-day timeframe often refers to the period within which it is most advantageous for consumers to discover and initiate a dispute after an error appears or is noticed. This period allows for a more effective and less complicated resolution process before errors become deeply entrenched or lead to further financial damage.
Why is 90 Days a Key Period?
- Timeliness for Investigation: Credit reporting agencies (Equifax, Experian, and TransUnion) are required to investigate disputes promptly. Initiating a dispute within 90 days of noticing an error ensures that the information is relatively fresh and easier to verify or correct by both the credit bureau and the data furnisher (the original creditor).
- Preventing Further Damage: The longer an error remains on your report, the more damage it can inflict on your credit score and financial opportunities. A 90-day credit challenge minimizes this prolonged negative impact.
- Statute of Limitations & Reporting Cycles: While not a direct statute of limitations for disputes, acting within 90 days aligns with typical credit reporting cycles and allows for corrections to appear on subsequent reports more quickly. This is especially important for individuals planning to apply for significant credit (like a mortgage) in the near future.
- Easier Documentation: It’s often easier to gather relevant documentation and evidence to support your claim if you address the issue promptly. Bank statements, payment records, and communication logs are more accessible and accurate when the event is recent.
- Avoiding "Stale" Disputes: While you can dispute errors older than 90 days, creditors and bureaus might find it harder to verify very old information, potentially complicating the process.
Identifying Credit Report Errors: Your First Step
The foundation of a successful 90-day credit challenge is identifying errors in the first place. Many consumers don’t regularly check their credit reports, leaving them vulnerable to inaccuracies. In 2026, it’s more important than ever to adopt a proactive approach.
How to Get Your Credit Reports:
You are entitled to a free copy of your credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) once every 12 months through AnnualCreditReport.com. Given the critical nature of these documents, consider staggering your requests throughout the year (e.g., one every four months) to maintain continuous oversight.
What to Look For:
When reviewing your reports, scrutinize every detail. Common errors include:
- Incorrect Personal Information: Misspellings of your name, wrong addresses, or incorrect phone numbers.
- Accounts You Don’t Recognize: This could be a sign of identity theft.
- Incorrect Account Status: Accounts listed as open when they’re closed, or vice versa; accounts incorrectly reported as delinquent.
- Duplicate Accounts: The same account listed multiple times.
- Incorrect Balances or Credit Limits: Discrepancies in reported amounts.
- Outdated Information: Negative information that should have been removed (most negative items fall off after seven years, bankruptcies after 10).
- Accounts from Divorced Spouses: If a joint account was closed or transferred, ensure it’s accurately reflected.
Initiating Your 90-Day Credit Challenge: The Dispute Process
Once you’ve identified an error, it’s time to act. Remember, the clock on your effective 90-day credit challenge starts ticking from when you first notice the error or when it appears on your report.
Step 1: Gather Your Evidence
Documentation is key. Collect any proof that supports your claim. This might include:
- Copies of your credit report highlighting the error.
- Bank statements or cancelled checks showing payments.
- Correspondence with creditors.
- Official documents like police reports (in cases of identity theft).
- Any other relevant records that prove the information is inaccurate.
Step 2: Contact the Credit Bureaus Directly
You have the right to dispute errors directly with each credit bureau that is reporting the incorrect information. You can do this online, by mail, or by phone. Written disputes sent via certified mail with a return receipt requested are often recommended as they provide a clear paper trail.
Your dispute letter should clearly state:
- Your full name, address, and social security number.
- A clear identification of the specific item(s) on your report that you are disputing.
- An explanation of why you believe the information is inaccurate.
- Copies of your supporting documentation (do not send originals).
- A request for the bureau to investigate and correct or remove the inaccurate information.
Step 3: Contact the Data Furnisher (Original Creditor)
While not legally required to initiate the dispute with the data furnisher, it’s often a good practice to contact them directly as well. They are the source of the information and can often correct errors more quickly. Send a similar letter with supporting documentation, requesting that they correct the information they’ve reported to the credit bureaus.
What Happens After You Initiate a Dispute?
Once you’ve submitted your 90-day credit challenge, the credit bureaus have a legal obligation under the FCRA to investigate. In most cases, they must complete their investigation within 30 days of receiving your dispute, though this can extend to 45 days if you provide additional information during the investigation period.
The Investigation Process:
- The credit bureau will forward your dispute and supporting documentation to the data furnisher.
- The data furnisher will then review the information and verify its accuracy.
- They will report their findings back to the credit bureau.
Possible Outcomes:
- Information is Corrected or Removed: If the investigation finds the information is inaccurate, incomplete, or unverifiable, it must be corrected or removed from your credit report.
- Information Remains: If the data furnisher verifies the information as accurate, it will remain on your report.
- Notification of Results: The credit bureau must inform you of the results of their investigation within five business days of its completion. If an item is changed or removed, you should also receive a revised copy of your credit report.
- Right to Add a Statement: If you disagree with the results of the investigation, you have the right to add a brief statement to your credit file explaining your side of the story. This statement will be included whenever your credit report is accessed.
Beyond the 90-Day Window: What If You Miss It?
While the 90-day credit challenge is highly recommended for optimal results, missing this informal window does not mean you forfeit your rights. The FCRA allows you to dispute inaccurate information at any time. However, the process might become more challenging if significant time has passed. Creditors might have purged older records, making verification more difficult. Therefore, while you can always dispute, the sooner you act, the better your chances of a swift and favorable resolution.
Preventative Measures for 2026 and Beyond
An ounce of prevention is worth a pound of cure, especially when it comes to your credit health. Here are some best practices to avoid future errors and ensure you’re always ready for a 90-day credit challenge if needed:
- Regularly Monitor Your Credit: Don’t just check once a year. Utilize credit monitoring services (many banks and credit card companies offer them for free) that alert you to changes on your report.
- Review All Financial Statements: Reconcile your bank and credit card statements with your records monthly. This can help you catch discrepancies before they even reach your credit report.
- Keep Meticulous Records: Maintain organized files of all your financial documents, including payment confirmations, loan agreements, and correspondence with creditors.
- Be Wary of Identity Theft: Protect your personal information online and offline. Use strong passwords, be cautious of phishing attempts, and shred sensitive documents.
- Understand Your Debts: Be fully aware of your repayment terms, due dates, and balances for all your credit accounts.
- Opt for Paperless Statements with Caution: While convenient, ensure you’re still reviewing your digital statements regularly. Sometimes physical mail can serve as a reminder.
Advanced Tips for Your 90-Day Credit Challenge
For those looking to maximize their chances of success, consider these advanced tips:
- Send Disputes to All Three Bureaus: If an error appears on multiple reports, dispute it with each bureau individually. Don’t assume one bureau will communicate with the others.
- Be Specific and Concise: While providing details, avoid emotional language. Stick to the facts and clearly state what you believe is wrong and why.
- Follow Up: If you don’t hear back within the stipulated timeframe, follow up with the credit bureau. Keep a log of all communications.
- Consider Professional Help: For complex cases or if you’re feeling overwhelmed, a reputable credit repair service or a consumer law attorney specializing in FCRA violations can provide invaluable assistance. Be cautious of services that promise unrealistic results or charge upfront fees.
- Understand "Reinsertion Rights": If an item is removed from your credit report as a result of your dispute, and the data furnisher later attempts to reinsert it, they must certify to the credit bureau that the information is complete and accurate. You must also be notified within five business days of the reinsertion.
The Future of Credit Reporting and Your Rights in 2026
As we move further into the 2020s, the financial technology (FinTech) sector continues to innovate, potentially bringing changes to how credit information is collected and used. While the core principles of the FCRA are likely to remain, consumers should stay informed about any new regulations or industry standards that might impact their credit rights. For instance, the discussion around alternative data (like utility payments or rent history) for credit scoring might evolve, making comprehensive monitoring even more crucial.
The emphasis on the 90-day credit challenge will likely grow stronger, as faster data processing means errors can propagate more quickly. Staying vigilant, understanding your rights, and acting decisively are your most powerful tools in maintaining a healthy credit profile.
Conclusion: Empowering Yourself with the 90-Day Credit Challenge
Your credit report is a dynamic document that reflects your financial journey. Ensuring its accuracy is not just about correcting mistakes; it’s about safeguarding your financial future, securing better opportunities, and protecting yourself from potential fraud. The 90-day credit challenge serves as a powerful reminder of the urgency and effectiveness of prompt action when you spot an error.
By regularly monitoring your credit reports, meticulously documenting any discrepancies, and understanding the step-by-step process of disputing errors, you empower yourself to take control of your financial narrative. Don’t let inaccurate information hold you back. Embrace the proactive approach, leverage your rights under the FCRA, and make the 90-day credit challenge a cornerstone of your personal financial management in 2026 and beyond. Your financial well-being depends on it.