Personal Finance Overhaul: Reducing Debt by 15% with Proven Strategies for 2026
Anúncios
In an increasingly complex financial landscape, taking control of your personal finances is not just a smart move; it’s a necessity. For many, debt can feel like an insurmountable mountain, casting a long shadow over future aspirations. However, with the right approach and a clear roadmap, achieving significant debt reduction is entirely within reach. This comprehensive guide will walk you through a personal finance overhaul, focusing on practical, proven debt reduction strategies designed to help you reduce your debt by a tangible 15% by 2026. This isn’t just about saving money; it’s about reclaiming financial freedom and building a more secure future.
Anúncios
The journey to becoming debt-free, or at least significantly less indebted, begins with understanding your current financial standing. It requires commitment, discipline, and a willingness to make adjustments to your spending habits and financial outlook. But rest assured, the rewards – peace of mind, increased savings, and greater financial flexibility – are well worth the effort. We’ll delve into everything from creating a realistic budget to implementing advanced debt repayment methods, ensuring you have all the tools necessary to succeed.
Understanding Your Debt Landscape: The First Step in Debt Reduction Strategies
Before you can embark on any effective debt reduction strategies, you must first gain a crystal-clear understanding of your current debt situation. This involves more than just knowing how much you owe; it means understanding who you owe, at what interest rates, and what the minimum payments are. This initial assessment is crucial for formulating a targeted and efficient repayment plan.
Anúncios
Gathering All Your Debt Information
Start by compiling a complete list of all your debts. This should include:
- Credit card balances
- Student loans
- Car loans
- Personal loans
- Medical bills
- Mortgage (if you plan to include it in your reduction efforts)
- Any other outstanding financial obligations
For each debt, note down the following:
- The creditor’s name
- The outstanding balance
- The interest rate (APR)
- The minimum monthly payment
- The due date
This detailed overview will serve as your baseline. Seeing all your debts laid out can be daunting, but it’s a necessary step towards taking control. It allows you to identify high-interest debts that are costing you the most and should be prioritized in your debt reduction strategies.
Calculating Your Debt-to-Income Ratio
Your debt-to-income (DTI) ratio is a key indicator of your financial health. It’s calculated by dividing your total monthly debt payments by your gross monthly income. Lenders use this ratio to assess your ability to manage monthly payments and repay debts. A high DTI ratio can signal financial strain and make it difficult to obtain new credit or loans. While there’s no single ‘ideal’ DTI, generally, a ratio below 36% is considered healthy. Understanding your DTI will help you set realistic goals for your debt reduction journey and gauge your progress.
Crafting a Realistic Budget: The Foundation of Effective Debt Reduction Strategies
A well-structured budget is the cornerstone of any successful financial plan, especially when it comes to debt reduction strategies. It allows you to track where your money is going, identify areas for savings, and allocate funds strategically towards your debt. Without a budget, it’s easy for expenses to spiral out of control, making debt repayment an uphill battle.
Tracking Your Income and Expenses
The first step in budgeting is to accurately track all your income and expenses. For income, include your net pay from all sources. For expenses, be meticulous. Categorize everything: housing, utilities, groceries, transportation, entertainment, dining out, subscriptions, and, of course, debt payments. You can use budgeting apps, spreadsheets, or even a simple notebook to record this information for at least a month, preferably two or three, to get a clear picture of your spending habits.
Identifying Areas for Spending Cuts
Once you have a clear picture of your spending, you can start identifying areas where you can cut back. Look for non-essential expenses that can be reduced or eliminated. This might include:
- Discretionary spending: Dining out less, reducing entertainment costs, cutting down on impulse purchases.
- Subscriptions: Review all your monthly subscriptions (streaming services, gym memberships, apps) and cancel those you rarely use.
- Transportation: Consider carpooling, using public transport, or walking/biking for shorter distances.
- Groceries: Plan your meals, make a shopping list, and stick to it to avoid unnecessary purchases. Cooking at home more often can save a significant amount.
Every dollar saved from these categories can be redirected towards your debt, accelerating your progress on your debt reduction strategies.
Setting Up a Debt-Focused Budget
With your spending cuts identified, adjust your budget to prioritize debt repayment. Allocate a specific amount each month that goes beyond your minimum payments. This extra payment is where the real magic of debt reduction happens. Remember, the goal is to reduce your debt by 15% by 2026, which means you need to consistently make more than the minimum payments.
Implementing Effective Debt Repayment Methods: Accelerating Your Progress
Once your budget is in place, it’s time to choose and implement specific debt reduction strategies that will help you tackle your outstanding balances. Two popular and highly effective methods are the debt snowball and debt avalanche.
The Debt Snowball Method
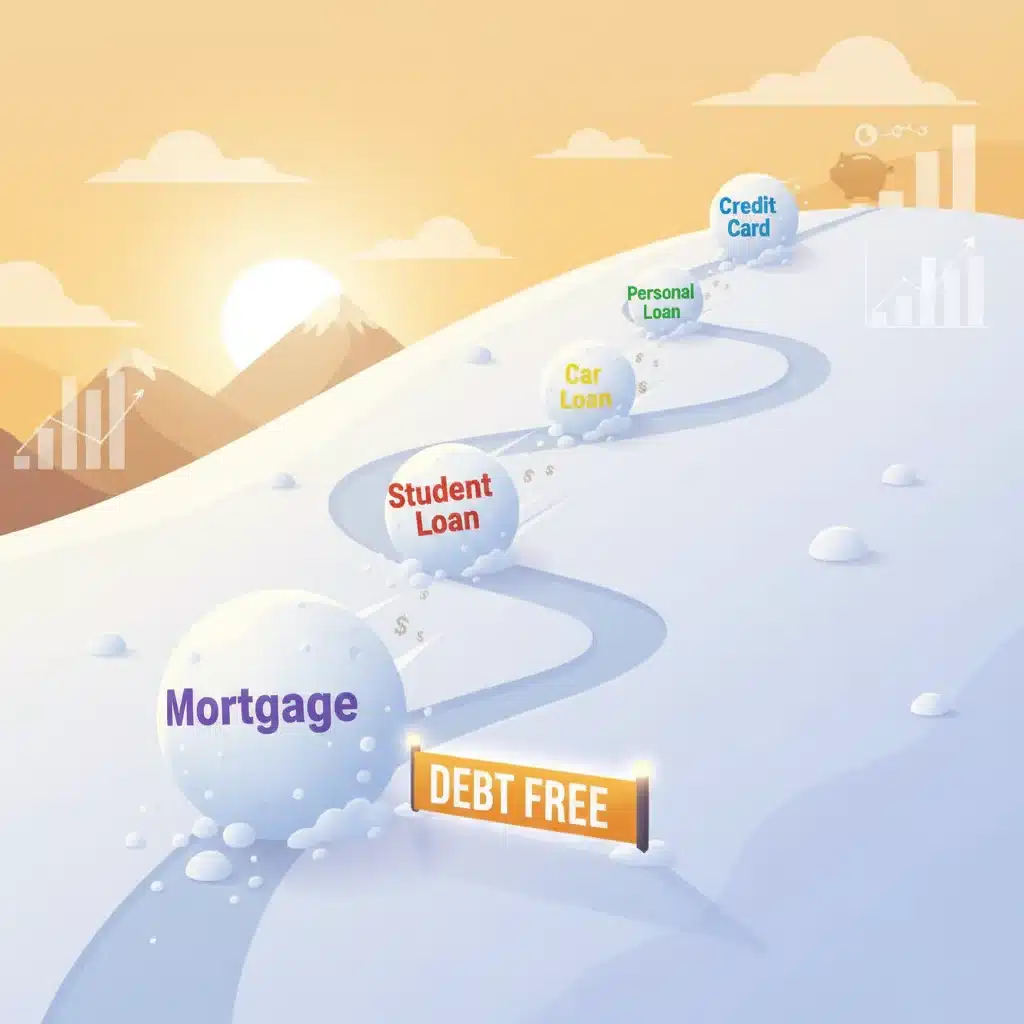
The debt snowball method involves paying off your debts in order from smallest balance to largest, regardless of the interest rate. Here’s how it works:
- List all your debts from the smallest balance to the largest.
- Make minimum payments on all debts except the smallest one.
- Throw all extra money you can muster at the smallest debt.
- Once the smallest debt is paid off, take the money you were paying on that debt (minimum payment + extra payment) and apply it to the next smallest debt.
- Repeat this process until all your debts are paid off.
The psychological wins you get from quickly paying off smaller debts can be incredibly motivating, keeping you engaged and committed to your debt reduction strategies. While it might cost slightly more in interest over the long run compared to the avalanche method, the behavioral benefits often outweigh this.
The Debt Avalanche Method
The debt avalanche method focuses on saving money on interest by paying off your debts in order from highest interest rate to lowest interest rate. Here’s how it works:
- List all your debts from the highest interest rate to the lowest.
- Make minimum payments on all debts except the one with the highest interest rate.
- Apply all extra money you have towards the debt with the highest interest rate.
- Once that debt is paid off, take the money you were paying on it and apply it to the debt with the next highest interest rate.
- Continue this process until all your debts are eliminated.
The debt avalanche method is mathematically more efficient, as it minimizes the total amount of interest you pay. If you’re disciplined and motivated by financial efficiency, this could be the ideal strategy for your debt reduction strategies.
Choosing the Right Method for You
The best method depends on your personality and what motivates you. If you need quick wins to stay motivated, the debt snowball might be better. If you’re focused on saving the most money on interest, the debt avalanche is the way to go. Both are powerful debt reduction strategies when applied consistently.
Exploring Additional Debt Reduction Strategies and Tools
Beyond budgeting and repayment methods, several other strategies and tools can significantly accelerate your debt reduction journey. These can help you lower interest rates, consolidate payments, or even increase your income to pay off debt faster.
Debt Consolidation and Refinancing
Debt consolidation involves combining multiple debts into a single, larger loan, often with a lower interest rate. This can simplify your payments and potentially reduce your overall interest costs. Options include:
- Personal Loans: Unsecured loans that can be used to pay off high-interest credit card debt.
- Balance Transfer Credit Cards: These cards offer a 0% introductory APR for a certain period (e.g., 12-18 months), allowing you to pay down principal without accruing interest. Be mindful of balance transfer fees and ensure you can pay off the transferred balance before the promotional period ends.
- Home Equity Loans or Lines of Credit (HELOCs): If you own a home, you might be able to borrow against your home equity. These often come with lower interest rates but carry the risk of putting your home up as collateral.
Refinancing, particularly for student loans or mortgages, can also lead to lower interest rates or more favorable repayment terms, freeing up more cash for other debt reduction strategies.
Negotiating with Creditors
Don’t underestimate the power of direct communication. If you’re struggling to make payments, contact your creditors. Many are willing to work with you to create a more manageable payment plan, temporarily reduce interest rates, or even settle for a lower lump sum payment, especially if you can demonstrate genuine hardship. This proactive approach can prevent late fees, protect your credit score, and provide much-needed breathing room in your debt reduction strategies.
Increasing Your Income
While cutting expenses is vital, increasing your income can significantly boost your debt repayment efforts. Consider:
- Side hustles: Freelancing, gig economy jobs, selling crafts, or offering services can provide extra income.
- Overtime at work: If available, working extra hours can be a quick way to earn more.
- Selling unused items: Declutter your home and sell items you no longer need on online marketplaces.
- Asking for a raise: If you’ve been performing well, negotiate for a higher salary.
Every additional dollar earned can be directly applied to your debt, accelerating your progress towards your 15% reduction goal.
Maintaining Momentum and Staying Motivated on Your Debt Reduction Journey
Debt reduction is a marathon, not a sprint. Staying motivated over the long term is crucial for achieving your goals. Here are some tips to help you maintain momentum and stick to your debt reduction strategies.
Set Realistic Milestones and Celebrate Small Wins
Breaking down your large goal (15% debt reduction by 2026) into smaller, achievable milestones can make the journey less overwhelming. Celebrate each small win, whether it’s paying off a small debt, hitting a certain payment threshold, or sticking to your budget for a full month. These celebrations don’t have to be expensive; a simple treat or acknowledgment can keep your spirits high.
Track Your Progress Visually
Visual aids can be incredibly powerful motivators. Create a debt thermometer, a spreadsheet with progress bars, or a chart that shows your debt decreasing over time. Seeing your progress visually can reinforce your efforts and remind you how far you’ve come, fueling your commitment to your debt reduction strategies.
Build an Emergency Fund
While it might seem counterintuitive to save money while trying to pay off debt, building a small emergency fund (e.g., $1,000) is a critical component of sustainable debt reduction strategies. This fund acts as a buffer against unexpected expenses, preventing you from incurring new debt when emergencies arise. Once you have a starter emergency fund, you can then focus more aggressively on debt repayment.
Educate Yourself Continuously
The world of personal finance is constantly evolving. Continuously educate yourself on financial literacy, investment opportunities, and new debt reduction strategies. Read books, listen to podcasts, follow reputable financial blogs, and attend webinars. The more knowledgeable you are, the better equipped you’ll be to make informed financial decisions and adapt your plan as needed.
Seek Support and Accountability
Share your goals with a trusted friend, family member, or partner who can offer support and hold you accountable. Consider joining online communities or forums dedicated to debt reduction. Sharing experiences, challenges, and successes with others on a similar journey can provide invaluable motivation and perspective.
Avoiding Common Pitfalls in Debt Reduction
Even with the best intentions and carefully planned debt reduction strategies, there are common pitfalls that can derail your progress. Being aware of these can help you navigate your journey more smoothly.
Beware of Lifestyle Creep
As your income increases or as you pay off debts, there’s a tendency for expenses to rise proportionally – this is known as lifestyle creep. Resist the urge to upgrade your lifestyle significantly until you’ve achieved your debt reduction goals. Continue living below your means and direct any extra funds towards debt or savings.
Don’t Get Discouraged by Setbacks
Life happens. Unexpected expenses, job changes, or health issues can sometimes force you to deviate from your plan. Don’t let a setback completely derail your efforts. Acknowledge it, adjust your budget and plan as needed, and get back on track as quickly as possible. Consistency, not perfection, is key to successful debt reduction strategies.
Avoid Taking on New Debt
While working to eliminate existing debt, it’s crucial to avoid taking on new debt, especially for non-essential items. If you’re using credit cards, make sure you pay off the full balance each month to avoid interest charges. If a purchase isn’t absolutely necessary and you can’t pay for it in cash, reconsider buying it.
Protect Your Credit Score
While focusing on debt reduction, don’t neglect your credit score. Making timely payments, keeping credit utilization low, and avoiding new credit applications will help maintain or even improve your score. A good credit score will be beneficial for your financial future once you’re debt-free.
The Long-Term Benefits of a Personal Finance Overhaul
Achieving a 15% debt reduction by 2026 is an ambitious yet entirely achievable goal that will lay a strong foundation for your long-term financial well-being. The benefits extend far beyond just having less debt.
Increased Financial Flexibility and Freedom
With less money going towards debt payments, you’ll have more disposable income. This newfound flexibility can be used to build a robust emergency fund, save for retirement, invest in your future, or even pursue personal goals that were previously out of reach.
Reduced Stress and Improved Well-being
Debt is a significant source of stress for many individuals. By actively working on your debt reduction strategies and seeing tangible progress, you’ll likely experience a significant reduction in financial anxiety, leading to improved mental and emotional well-being.
Better Financial Habits
The process of overhauling your personal finances and reducing debt instills valuable habits such as diligent budgeting, mindful spending, and disciplined saving. These habits will serve you well for the rest of your life, ensuring you maintain a strong financial footing long after your debt is gone.
Opportunities for Wealth Building
Once you’ve significantly reduced your debt, the money that was once allocated to payments can be redirected towards wealth-building activities. This could mean maximizing your retirement contributions, investing in the stock market, or saving for a down payment on a home. Your financial future will look significantly brighter.
Conclusion: Your Path to a Debt-Reduced Future by 2026
Embarking on a personal finance overhaul with the goal of reducing your debt by 15% by 2026 is a journey that requires dedication and strategic planning. By understanding your debt, crafting a realistic budget, implementing proven debt reduction strategies like the snowball or avalanche methods, and leveraging additional tools like consolidation or income generation, you are setting yourself up for profound financial success.
Remember that consistency, patience, and a positive mindset are your greatest allies. Celebrate your milestones, learn from any setbacks, and keep your long-term financial freedom in sight. The effort you put in now will pay dividends for years to come, transforming your relationship with money and paving the way for a more secure and prosperous future. Start today, take that first step, and commit to the powerful change that a focused debt reduction plan can bring to your life.
Autor