Understanding the 2026 Medicare Part B Premium Changes: What 65 Million Beneficiaries Need to Know Now
As millions of Americans rely on Medicare for their healthcare needs, understanding potential changes to premiums is paramount for financial planning and peace of mind. With 65 million beneficiaries currently enrolled, the prospect of adjustments to Medicare Part B premiums in 2026 is a topic of significant interest and concern. This comprehensive guide aims to demystify the factors influencing these costs, explain what beneficiaries can expect, and provide actionable strategies to navigate the evolving landscape of Medicare expenses.
Anúncios
The Centers for Medicare & Medicaid Services (CMS) typically announces premium adjustments annually, but foresight into potential future changes allows beneficiaries to plan more effectively. While 2026 might seem distant, the trends and economic indicators that shape these decisions are already in motion. Therefore, proactively understanding the potential shifts in Medicare Part B 2026 premiums is not just prudent; it’s essential for safeguarding your healthcare budget and ensuring continued access to vital medical services.
This article will delve into the intricacies of Medicare Part B, explore the historical context of premium adjustments, analyze the key drivers behind cost increases, and offer practical advice for preparing for Medicare Part B 2026 changes. Whether you are a current beneficiary, approaching Medicare eligibility, or a caregiver, this information will equip you with the knowledge needed to make informed decisions about your healthcare future.
Anúncios
What is Medicare Part B and Why Do Premiums Change?
Medicare Part B is a crucial component of Original Medicare, covering medically necessary services and preventive services. This includes doctor’s visits, outpatient care, durable medical equipment, and certain home health services. Unlike Part A, which often has no premium for most beneficiaries, Part B requires a monthly premium. This premium is typically deducted directly from Social Security benefits, Railroad Retirement Board benefits, or federal retirement annuities.
The premiums for Medicare Part B 2026, like in previous years, are not static. Several complex factors contribute to their annual adjustments. These include:
- Healthcare Spending Trends: Overall national healthcare expenditures play a significant role. Increases in the cost of medical services, prescription drugs, and new medical technologies can drive up Part B costs.
- Utilization of Services: Higher utilization rates of Part B services by beneficiaries can also lead to premium increases.
- Economic Factors: Inflation, the general cost of living, and wage growth can indirectly influence premium calculations.
- Congressional Mandates and Legislation: Policy changes enacted by Congress can directly impact Medicare funding and, consequently, premium amounts.
- Trust Fund Solvency: While Part B is primarily funded by premiums and general revenue, the overall financial health of the Medicare trust funds is always a consideration.
- Hold Harmless Provision: This provision generally prevents most beneficiaries from seeing their Part B premium increase by more than the dollar amount of their Social Security cost-of-living adjustment (COLA). However, there are exceptions, particularly for new enrollees, those not receiving Social Security benefits, and those subject to the Income-Related Monthly Adjustment Amount (IRMAA).
Understanding these underlying mechanisms is the first step in anticipating and preparing for the Medicare Part B 2026 premium landscape. It’s a dynamic system influenced by a multitude of variables, making proactive monitoring and planning indispensable.
Historical Context: A Look at Past Medicare Part B Premium Adjustments
To better understand what might influence Medicare Part B 2026 premiums, it’s helpful to examine historical trends. Over the past decade, Part B premiums have seen both modest increases and, occasionally, more significant jumps. For instance, there have been years where the premium increase was relatively small due to a low Social Security COLA, triggering the hold harmless provision for many. Conversely, there have been years with substantial increases, often driven by rising healthcare costs or legislative changes.
For example, in some years, a significant increase in the cost of a new drug or a new medical procedure covered by Part B has led to a noticeable premium hike. Similarly, broader economic shifts or changes in healthcare policy can have a ripple effect. This historical volatility underscores the importance of not assuming premiums will remain constant and highlights the need for beneficiaries to budget with potential increases in mind for Medicare Part B 2026 and beyond.
Examining these patterns helps us appreciate that while the exact figures for 2026 are not yet known, the factors driving these changes are consistent. Keeping an eye on healthcare inflation, pharmaceutical costs, and legislative discussions can offer early clues about what’s to come.
Projecting the 2026 Medicare Part B Premium: Key Influencers
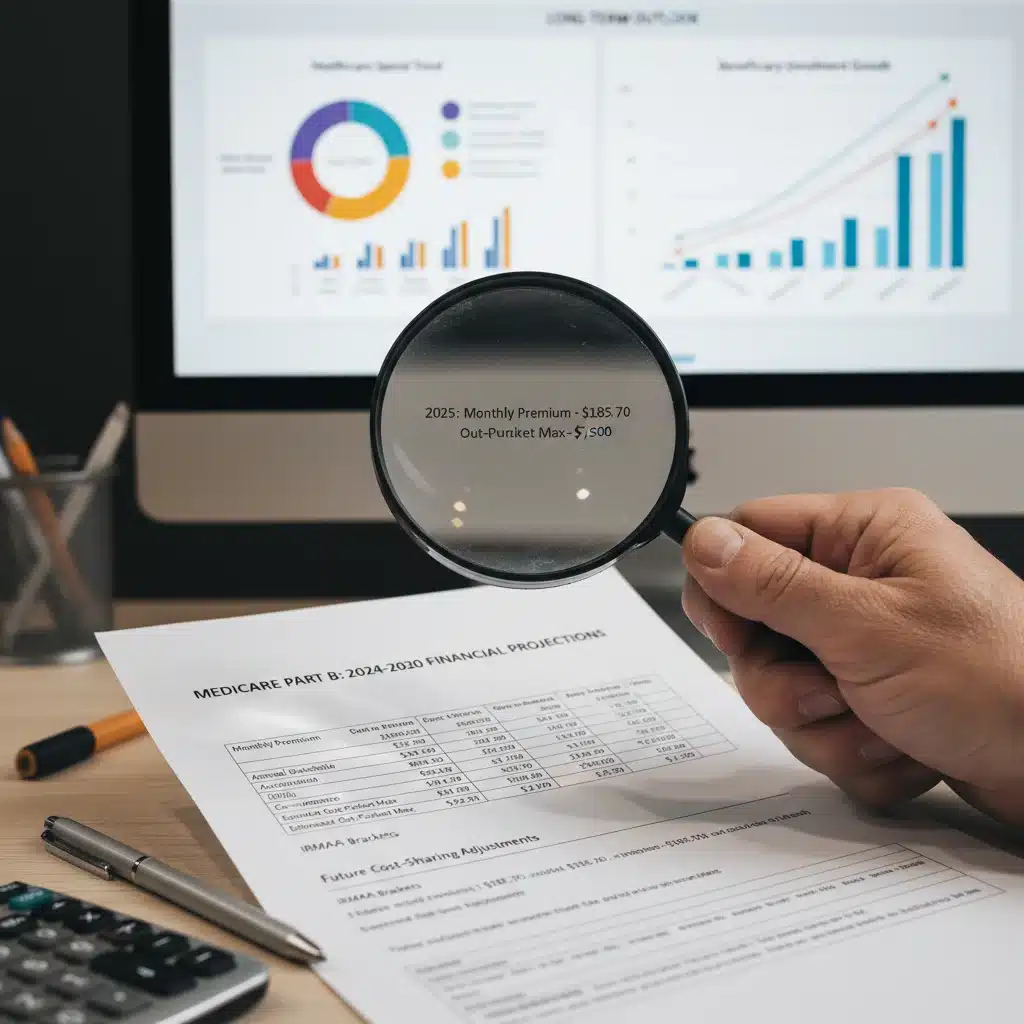
While specific numbers for Medicare Part B 2026 premiums won’t be released until late 2025, we can identify several key influencers that will likely shape the final figures. These are the aspects that beneficiaries, policymakers, and analysts will be closely watching:
Inflation and Economic Outlook
The broader economic environment, particularly inflation, plays a crucial role. High inflation drives up the cost of goods and services across the board, including healthcare. If inflationary pressures persist or intensify, it will inevitably translate into higher operational costs for healthcare providers, which can then be reflected in Medicare spending and, subsequently, Part B premiums. The Social Security COLA, which is tied to inflation, also indirectly influences Part B premiums for many beneficiaries due to the hold harmless provision. A higher COLA might allow for a larger premium increase for those protected.
Healthcare Utilization and Innovation
The rate at which beneficiaries utilize Part B services is another critical factor. An aging population, combined with advancements in medical technology and treatments, often leads to increased utilization. While these innovations improve health outcomes, they frequently come with higher price tags. New diagnostic tests, cutting-edge therapies, and more frequent doctor visits all contribute to the overall expenditure. Therefore, monitoring trends in healthcare utilization and the introduction of new, costly medical interventions will be vital for predicting Medicare Part B 2026 premium movements.
Pharmaceutical Costs
Prescription drugs covered under Part B (primarily those administered in a doctor’s office or outpatient setting, not self-administered retail prescriptions covered by Part D) can significantly impact premiums. The cost of specialty drugs, biologics, and new breakthrough medications can be extraordinarily high. If several expensive new drugs are approved and widely adopted by 2026, it could exert upward pressure on Part B costs. Ongoing efforts to control drug prices, such as those introduced through recent legislation, could potentially mitigate some of these increases, but their full impact on Medicare Part B 2026 remains to be seen.
Legislative and Policy Changes
Government policies and legislative actions can have a direct and immediate effect on Medicare funding and structure. Congress could pass new laws that alter how Part B premiums are calculated, change the services covered, or introduce new revenue streams or cost-saving measures. For example, discussions around Medicare solvency, means-testing for premiums, or expanding benefits could all lead to adjustments. Beneficiaries should stay informed about any proposed legislation related to Medicare as it could significantly alter the outlook for Medicare Part B 2026.
Who Will Be Affected by 2026 Medicare Part B Premium Changes?
While premium changes affect all 65 million Medicare beneficiaries to some degree, the impact can vary significantly based on individual circumstances. Understanding these nuances is crucial for personalized planning for Medicare Part B 2026.
Most Beneficiaries (Protected by Hold Harmless)
A significant portion of beneficiaries will likely be protected by the “hold harmless” provision. This rule states that your Part B premium increase cannot be greater than the dollar increase in your Social Security benefit’s cost-of-living adjustment (COLA). This means that for many, their net Social Security payment will not decrease due to a Part B premium hike. However, this protection doesn’t mean their premium won’t increase; it simply limits the increase to ensure their Social Security check doesn’t shrink.
New Enrollees and High-Income Beneficiaries (IRMAA)
The hold harmless provision does not apply to everyone. Specifically, new Medicare enrollees, those who don’t receive Social Security benefits (or whose benefits are too low), and those who pay the Income-Related Monthly Adjustment Amount (IRMAA) are not protected. IRMAA affects beneficiaries with higher incomes, requiring them to pay a higher Part B premium. For these individuals, the full premium increase for Medicare Part B 2026 will apply, potentially resulting in a more substantial financial impact.
IRMAA thresholds are adjusted annually, and if your income has increased, you might find yourself in a higher IRMAA bracket, leading to a double impact: a general premium increase compounded by a higher income-related adjustment. It’s essential for higher-income beneficiaries to be particularly vigilant about potential premium changes.
Beneficiaries with Medicare Advantage Plans
Even if you are enrolled in a Medicare Advantage (Part C) plan, you generally still need to pay your Part B premium. Medicare Advantage plans are offered by private companies approved by Medicare and often include Part A, Part B, and sometimes Part D coverage. While some Advantage plans may offer a partial rebate of the Part B premium, the underlying Part B premium set by CMS for Medicare Part B 2026 will still be a factor in your overall healthcare costs.
Strategies for Preparing for 2026 Medicare Part B Premium Changes
While the exact figures for Medicare Part B 2026 are yet to be determined, proactive planning can significantly mitigate the impact of potential premium increases. Here are several strategies beneficiaries can employ:
1. Review Your Budget and Financial Plan
Start by thoroughly reviewing your current monthly budget, specifically focusing on healthcare expenses. Identify how much you currently allocate to Medicare Part B premiums and other medical costs. Then, create a contingency plan that accounts for a potential increase in your Medicare Part B 2026 premium. Even a modest increase can add up over a year. Consider setting aside a small amount each month into a dedicated savings account to absorb future premium hikes.
If you anticipate being subject to IRMAA, factor in potentially larger increases. Understanding your current and projected income levels is crucial for this assessment.
2. Explore Medicare Savings Programs (MSPs)
For beneficiaries with limited income and resources, Medicare Savings Programs (MSPs) can be a lifeline. These state-run programs can help pay for Part B premiums, deductibles, coinsurance, and copayments. There are different types of MSPs, each with varying income and resource limits. Even if you didn’t qualify in the past, it’s worth checking again as eligibility criteria can change, and your financial situation might have shifted. Applying for an MSP could significantly reduce your out-of-pocket costs for Medicare Part B 2026.
3. Understand IRMAA and Income Planning
If you are a higher-income beneficiary, understanding the Income-Related Monthly Adjustment Amount (IRMAA) is critical. IRMAA is based on your modified adjusted gross income (MAGI) from two years prior. For Medicare Part B 2026, your 2024 income will be used to determine if you owe IRMAA. If you anticipate a significant income event in 2024 (e.g., selling an asset, large Roth conversion, significant capital gains), be aware that this could impact your 2026 premiums.
Consider consulting with a financial advisor to strategically manage your income, especially if you are close to an IRMAA threshold. There are legitimate strategies to lower your MAGI, such as tax-loss harvesting, qualified charitable distributions from IRAs, or careful timing of retirement account withdrawals, which could help reduce or avoid IRMAA for Medicare Part B 2026.
4. Evaluate Your Medicare Advantage Plan (if applicable)
If you are enrolled in a Medicare Advantage plan, remember that you still pay the Part B premium. During the Annual Enrollment Period (AEP) each fall, review your current plan and compare it with other options available for 2026. Some plans offer Part B premium rebates, which can offset some of the costs. Ensure your plan continues to meet your healthcare needs and budget, considering any potential changes to the underlying Medicare Part B 2026 premium.
5. Stay Informed and Monitor Announcements
The most effective strategy is to stay informed. CMS typically announces the following year’s Medicare premiums, deductibles, and coinsurance amounts in the fall (usually late October or early November). Pay close attention to these announcements as they will provide the definitive figures for Medicare Part B 2026. Reliable sources include the official Medicare.gov website, CMS press releases, and reputable financial news outlets.
The Role of Advocacy and Policy in Medicare Part B Premiums
The determination of Medicare Part B 2026 premiums is not solely an actuarial exercise; it is also influenced by policy debates and advocacy efforts. Various organizations, including those representing seniors, healthcare providers, and consumer advocates, regularly engage with Congress and CMS to influence Medicare policy. These groups often highlight the financial burden of rising premiums on beneficiaries and advocate for measures that promote affordability and access to care.
Current legislative discussions often revolve around controlling healthcare costs, particularly pharmaceutical prices, and ensuring the long-term solvency of Medicare. The outcomes of these discussions can directly impact future premium adjustments. For instance, if legislation is passed that effectively lowers drug costs covered by Part B, it could potentially temper premium increases. Conversely, if new, expensive treatments become widely available without corresponding cost controls, premiums could rise more sharply.
Beneficiaries and their families can also play a role by staying informed about these policy debates and, if they choose, by contacting their elected officials to voice their concerns about Medicare affordability. Collective advocacy can sometimes influence the direction of healthcare policy, which in turn affects the financial landscape of Medicare Part B 2026 and beyond.
Common Misconceptions About Medicare Part B Premiums
Navigating Medicare can be complex, and several misconceptions often arise regarding Part B premiums. Dispelling these can help beneficiaries better prepare for Medicare Part B 2026.
- Misconception: My Part B premium will never increase. While the hold harmless provision protects many from seeing their Social Security check decrease, it does not mean your premium won’t go up. It simply limits the increase to your COLA. For those not protected, increases can be significant.
- Misconception: My Medicare Advantage plan covers my Part B premium. While some Medicare Advantage plans offer a partial rebate of the Part B premium, you are still responsible for paying the underlying Part B premium to Medicare. The rebate only offsets a portion of that cost.
- Misconception: My income doesn’t affect my Part B premium. This is incorrect for higher-income beneficiaries. If your modified adjusted gross income exceeds certain thresholds, you will pay IRMAA, which is an additional amount added to your standard Part B premium.
- Misconception: I can opt out of Part B if the premium is too high. While you can delay enrolling in Part B if you have creditable employer coverage, once you are enrolled, opting out without creditable coverage can lead to lifelong late enrollment penalties if you decide to re-enroll later.
Understanding these distinctions is crucial for accurate financial planning and avoiding unwelcome surprises when the Medicare Part B 2026 premiums are announced.
Conclusion: Proactive Planning is Key for 2026 Medicare Part B Premiums
The prospect of changes to Medicare Part B 2026 premiums is a significant consideration for the 65 million beneficiaries who rely on this vital program. While the exact figures remain to be seen, the underlying factors influencing these costs – healthcare spending, inflation, utilization rates, and policy decisions – are constantly in motion. By understanding these dynamics, reviewing your financial situation, exploring assistance programs, and staying informed, you can effectively prepare for potential adjustments.
Proactive planning is not merely about anticipating higher costs; it’s about ensuring uninterrupted access to the healthcare services you need. Engage with financial advisors, utilize official Medicare resources, and keep a close eye on announcements from CMS. By taking these steps now, you can confidently navigate the evolving landscape of Medicare Part B 2026 and secure your healthcare future.
Remember, Medicare is a cornerstone of health security for millions of Americans. Being well-informed and prepared for changes, particularly to essential components like Part B premiums, empowers you to make the best decisions for your health and financial well-being.