Comparing 2026 Federal Student Loan Forgiveness Programs: Which Option Offers the Best Relief for Your Debt?
Anúncios
Student loan debt has become a significant burden for millions across the United States, impacting financial futures, life choices, and overall economic stability. As we look towards 2026, the landscape of federal student loan forgiveness programs continues to evolve, offering potential pathways to relief for many borrowers. Understanding these programs, their eligibility criteria, and their benefits is crucial for anyone navigating the complexities of student debt. This comprehensive guide aims to demystify the various federal student loan forgiveness 2026 options, helping you identify which program might offer the best relief for your specific situation.
Anúncios
The federal government has, over the years, introduced and modified several initiatives designed to alleviate the burden of student loans. These programs are not one-size-fits-all; they cater to different professions, financial circumstances, and repayment histories. For many, the prospect of student loan forgiveness 2026 represents a beacon of hope, a chance to shed a significant financial weight and move forward with greater financial freedom. However, the details can be intricate, and a clear understanding is paramount to successfully applying for and receiving the benefits of these programs.
Understanding the Current Student Loan Landscape for 2026
Before delving into specific forgiveness programs, it’s essential to grasp the broader context of federal student loans as we approach 2026. The student loan environment is dynamic, with policy changes, economic shifts, and legislative updates constantly shaping the available options. The COVID-19 pandemic brought unprecedented pauses and adjustments to student loan repayment, which have now largely concluded, pushing borrowers back into regular payment schedules. This return to repayment underscores the urgency for many to explore student loan forgiveness 2026 opportunities.
Anúncios
Federal student loans, unlike private loans, come with a range of borrower protections and repayment flexibilities, including access to income-driven repayment (IDR) plans and various forgiveness programs. These options are designed to prevent default and provide a safety net for borrowers facing financial hardship. As of 2026, the core federal forgiveness programs are expected to remain in place, though specific rules and eligibility requirements may see minor adjustments based on ongoing legislative discussions and administrative decisions. Staying informed about these potential changes is a critical step in effective debt management.
The sheer volume of outstanding student loan debt in the U.S. highlights the necessity of these programs. For many, navigating this debt without a clear path to reduction or forgiveness can feel overwhelming. This article will break down the most prominent federal student loan forgiveness 2026 programs, providing actionable insights into each. We will cover programs like Public Service Loan Forgiveness (PSLF), Income-Driven Repayment (IDR) forgiveness, and other specialized programs, offering a comparative analysis to help you make an informed decision.
Public Service Loan Forgiveness (PSLF): A Lifeline for Public Servants
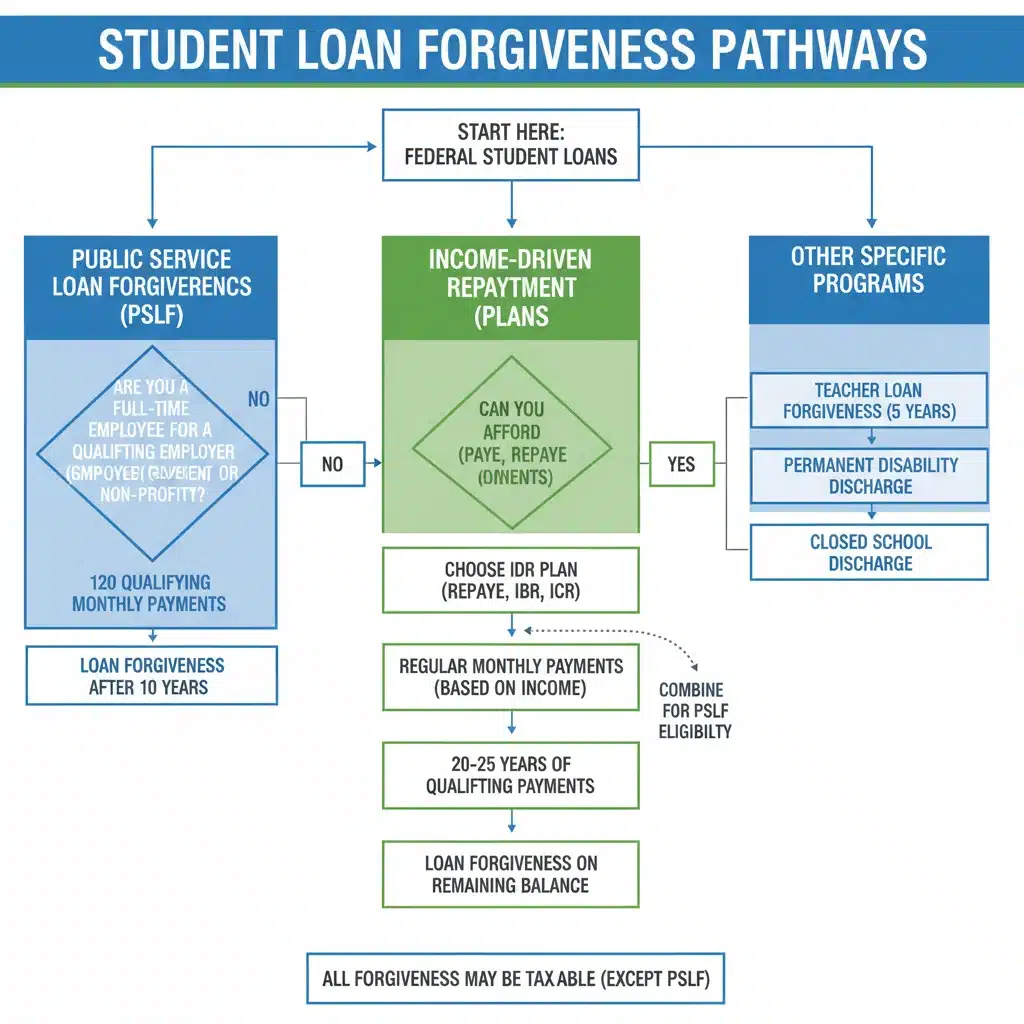
The Public Service Loan Forgiveness (PSLF) program is arguably one of the most well-known and impactful federal student loan forgiveness 2026 initiatives. Designed to encourage careers in public service, PSLF offers tax-free forgiveness of the remaining balance on Direct Loans after 120 qualifying monthly payments have been made under a qualifying repayment plan while working full-time for a qualifying employer.
Eligibility for PSLF
To be eligible for PSLF, borrowers must meet several strict criteria:
- Loan Type: Only Direct Loans are eligible. If you have Federal Family Education Loan (FFEL) Program loans or Federal Perkins Loans, you may need to consolidate them into a Direct Consolidation Loan to qualify. It’s crucial to do this before making significant progress on qualifying payments, as consolidation creates a new loan with a new payment count.
- Employment: You must be employed full-time by a U.S. federal, state, local, or tribal government organization, or a non-profit organization that is tax-exempt under Section 501(c)(3) of the Internal Revenue Code. Certain other non-profit organizations that provide specific public services may also qualify.
- Repayment Plan: Payments must be made under a qualifying income-driven repayment (IDR) plan. These include the Revised Pay As You Earn (REPAYE) Plan, Pay As You Earn (PAYE) Plan, Income-Based Repayment (IBR) Plan, and Income-Contingent Repayment (ICR) Plan. The Standard Repayment Plan also qualifies, but you would repay your loan in full before reaching 120 payments.
- Number of Payments: You must make 120 qualifying monthly payments. These payments do not need to be consecutive, meaning you can change jobs or repayment plans and still work towards the 120 payments.
Benefits and Considerations for PSLF
The primary benefit of PSLF is the complete forgiveness of your remaining Direct Loan balance, tax-free. This can amount to tens or even hundreds of thousands of dollars in debt relief, making it an extremely attractive option for those committed to public service careers. However, PSLF requires a significant commitment, typically 10 years of qualifying employment and payments.
It’s vital for borrowers pursuing PSLF to track their employment and payments meticulously. The Department of Education provides an Employment Certification Form (ECF) that should be submitted annually or whenever you change employers. This helps confirm that your employment and payments are on track, preventing potential issues when applying for forgiveness. The PSLF Help Tool is an invaluable resource for this process.
For 2026, PSLF is expected to continue as a cornerstone of federal student loan forgiveness. Potential updates might include clarifications on qualifying employment or slight adjustments to the application process, but the core structure is anticipated to remain stable. Borrowers should continue to monitor official student aid websites for the latest information.
Income-Driven Repayment (IDR) Plan Forgiveness: Long-Term Relief
Income-Driven Repayment (IDR) plans are designed to make federal student loan payments more manageable by capping them at a percentage of your discretionary income. A significant feature of these plans is the promise of student loan forgiveness 2026 after a specified period of repayment, typically 20 or 25 years, depending on the plan and whether you have graduate or undergraduate loans.
Types of IDR Plans and Their Forgiveness Terms
There are several IDR plans, each with slightly different terms for forgiveness:
- Revised Pay As You Earn (REPAYE) Plan: Payments are generally 10% of discretionary income. Remaining balances are forgiven after 20 years of payments for undergraduate loans and 25 years for graduate or professional study loans.
- Pay As You Earn (PAYE) Plan: Payments are generally 10% of discretionary income, but never more than what you would pay under the Standard Repayment Plan. Remaining balances are forgiven after 20 years of payments.
- Income-Based Repayment (IBR) Plan: Payments are generally 10% or 15% of discretionary income, depending on when you took out your loans, and never more than the Standard Repayment Plan amount. Remaining balances are forgiven after 20 or 25 years of payments.
- Income-Contingent Repayment (ICR) Plan: Payments are the lesser of 20% of your discretionary income or what you would pay on a fixed 12-year repayment plan adjusted by income. Remaining balances are forgiven after 25 years of payments.
The SAVE Plan: A New Horizon for IDR
The Biden administration introduced the Saving on a Valuable Education (SAVE) Plan, which is an enhanced version of the REPAYE plan. For 2026, the SAVE plan is expected to be fully implemented and will offer some of the most generous terms for borrowers. Key features of the SAVE plan include:
- Lower Payments: Payments for undergraduate loans are reduced from 10% to 5% of discretionary income. Payments for graduate loans remain at 10%, and a weighted average is applied for borrowers with both types of loans.
- Interest Subsidy: If your monthly payment doesn’t cover the accrued monthly interest, the government covers the remaining interest, preventing your loan balance from growing due to unpaid interest.
- Shorter Forgiveness Period for Smaller Balances: Borrowers with original principal balances of $12,000 or less may receive forgiveness after as few as 10 years of payments, with an additional year added for every $1,000 borrowed above $12,000, up to the standard 20 or 25 years.
The SAVE plan represents a significant improvement for many borrowers, especially those with lower incomes or smaller loan balances. It’s a crucial component of student loan forgiveness 2026 strategies for many.
Tax Implications of IDR Forgiveness
Unlike PSLF, the forgiven amount under IDR plans may be considered taxable income by the IRS. This is a critical distinction that can significantly impact the net benefit of IDR forgiveness. However, there have been temporary legislative changes, such as those under the American Rescue Plan, that have made IDR forgiveness tax-free through December 31, 2025. Borrowers anticipating IDR forgiveness in 2026 and beyond should consult a tax professional to understand the potential tax liability, as the tax-free status may not be extended.
Despite the potential tax implications, IDR plans offer invaluable protection against default and provide a structured path to eventual forgiveness, making them a cornerstone of federal student loan forgiveness 2026 for many borrowers who do not qualify for PSLF or other specialized programs.
Teacher Loan Forgiveness (TLF): Rewarding Educators
The Teacher Loan Forgiveness (TLF) program is specifically designed to support educators. It offers forgiveness for up to $17,500 on Direct Subsidized and Unsubsidized Loans and Subsidized and Unsubsidized Federal Stafford Loans after five consecutive complete years of full-time teaching in a low-income school or educational service agency.
Eligibility for TLF
Key eligibility requirements for TLF include:
- Loan Type: Direct Subsidized/Unsubsidized Loans and Subsidized/Unsubsidized Federal Stafford Loans.
- Teaching Service: You must teach full-time for five complete and consecutive academic years in a school or educational service agency that serves low-income students. The U.S. Department of Education publishes an annual directory of Low-Income Schools for Teacher Loan Forgiveness.
- Highly Qualified Teacher: You must be a highly qualified teacher as defined by federal guidelines at the time of your service.
Benefits and Considerations for TLF
The amount of forgiveness depends on the subject taught. Highly qualified math and science teachers at the secondary level, and highly qualified special education teachers at the elementary or secondary level, can receive up to $17,500 in forgiveness. Other eligible teachers can receive up to $5,000. This forgiveness is also tax-free.
It’s important to note that you cannot receive both PSLF and TLF for the same period of service. If you qualify for both, you’ll need to choose which program best suits your long-term debt relief goals. For many teachers, especially those with moderate loan balances, TLF can provide quicker relief than PSLF’s 10-year requirement.
For 2026, TLF is expected to continue supporting educators, providing a valuable incentive for teaching in underserved communities. Educators should verify their school’s eligibility and ensure they meet the highly qualified teacher criteria.
Other Specialized Federal Loan Forgiveness and Discharge Options
Beyond PSLF, IDR, and TLF, several other federal student loan forgiveness 2026 options and discharge programs exist, catering to specific circumstances. While not as broadly applicable, they are vital for those who qualify.
Total and Permanent Disability (TPD) Discharge
Borrowers who are totally and permanently disabled may be eligible for a Total and Permanent Disability (TPD) Discharge, which forgives all their federal student loans. Eligibility can be demonstrated through documentation from the Department of Veterans Affairs (VA), the Social Security Administration (SSA), or a physician’s certification. This discharge is generally tax-free.
Borrower Defense to Repayment Discharge
This program offers relief to borrowers whose schools engaged in misconduct, such as misleading students about job prospects or the quality of their education. If a borrower can prove they were defrauded by their school, their federal student loans may be discharged. The Department of Education periodically announces findings against specific institutions, making it easier for affected students to apply.
Closed School Discharge
If your school closed while you were enrolled or shortly after you withdrew, and you were unable to complete your program, you might be eligible for a Closed School Discharge. This discharges your federal student loans related to that school, provided you did not transfer your credits to another school or complete a comparable program elsewhere.
False Certification Discharge
This discharge applies if your school falsely certified your eligibility to receive federal student loans. This can happen in cases of identity theft, or if the school certified your ability to benefit from their program when you clearly lacked the necessary qualifications.
Perkins Loan Cancellation
Federal Perkins Loans, while no longer disbursed, still exist for many borrowers. These loans have their own cancellation provisions for individuals who work in certain public service professions, such as teachers, nurses, law enforcement officers, and early intervention specialists. The percentage of the loan that can be canceled increases with each year of qualifying service.
Comparing Your Best Options for Student Loan Forgiveness 2026
Choosing the best student loan forgiveness 2026 program depends entirely on your individual circumstances. Here’s a comparative overview to help you decide:
- If you work in public service (government or eligible non-profit): PSLF is likely your best bet, offering tax-free forgiveness after 10 years of payments. Ensure your loans are Direct Loans and you are on an IDR plan.
- If you are an educator in a low-income school: TLF offers quicker forgiveness (5 years) for up to $17,500. Consider this if your loan balance is modest, or if you prefer a shorter commitment. Remember, you can’t double-dip on service periods for PSLF and TLF.
- If you have high debt relative to your income, or don’t qualify for PSLF/TLF: An Income-Driven Repayment (IDR) plan, particularly the new SAVE plan, is crucial. It makes payments affordable and leads to forgiveness after 20-25 years. Be mindful of potential tax implications at the time of forgiveness, though current legislation has temporarily made it tax-free.
- If you have a disability: TPD Discharge can provide complete relief.
- If you were defrauded by your school or your school closed: Borrower Defense or Closed School Discharge could be applicable.
Key Considerations for All Borrowers
Regardless of the path you choose, several general principles apply to maximizing your chances for student loan forgiveness 2026:
- Understand Your Loan Types: Federal loans offer these benefits; private loans do not. Consolidate FFEL or Perkins loans into Direct Loans if necessary for PSLF or most IDR plans.
- Enroll in the Right Repayment Plan: Forgiveness programs often require enrollment in specific IDR plans.
- Track Your Progress: Especially for PSLF and IDR forgiveness, keep meticulous records of your payments, employment, and annual certifications.
- Stay Informed: Federal student loan policies can change. Regularly check official sources like StudentAid.gov for the latest updates.
- Beware of Scams: Only trust information from official sources. Never pay for services that promise to get you forgiveness that you can apply for yourself for free.
- Annual Recertification: If you are on an IDR plan, you must recertify your income and family size annually. Failure to do so can result in higher payments and a loss of interest subsidies.
The Future of Student Loan Forgiveness Beyond 2026
While this guide focuses on student loan forgiveness 2026, it’s important to acknowledge that the landscape is continually evolving. Discussions around broader student loan relief, including potential executive actions or legislative changes, are ongoing. While the specifics of such future initiatives are uncertain, the existing framework of federal forgiveness programs provides a stable foundation for borrowers seeking relief.
Advocates continue to push for more expansive forgiveness, citing economic benefits and the need for greater equity. Conversely, some policymakers argue for stricter eligibility or fewer programs. These debates highlight the importance of staying engaged with financial news and official government announcements. However, for the foreseeable future, the programs outlined above are the most reliable avenues for federal student loan forgiveness 2026.
Borrowers should not wait for potential future changes but should instead actively pursue the relief options currently available to them. Proactive engagement with your student loan servicer and thorough understanding of your eligibility for existing programs are your best strategies for managing your debt effectively.
Conclusion: Charting Your Course to Debt Relief in 2026
Navigating federal student loan forgiveness 2026 can seem daunting, but with a clear understanding of the available programs, you can chart a strategic course toward debt relief. Whether you are a dedicated public servant, a committed educator, or a borrower facing financial hardship, there is likely a federal program designed to help you. The key is to identify the program that aligns with your professional path and financial situation, understand its specific requirements, and diligently follow the application process.
Remember to regularly check your loan status, communicate with your loan servicer, and utilize official resources like StudentAid.gov. By taking these proactive steps, you can significantly improve your chances of achieving student loan forgiveness and moving closer to a debt-free future. The journey to financial freedom is a marathon, not a sprint, and understanding your options for student loan forgiveness 2026 is a crucial stride in that journey.
Autor